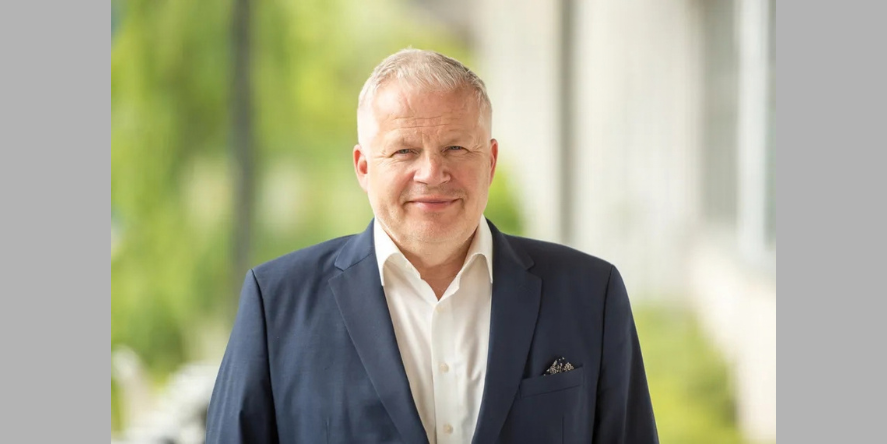

By Vikas Panchal, Business Head- Middle East, Tally Solutions
Small businesses, start-ups and freelancers are experiencing major shifts in business operations due to the COVID-19 pandemic. With most of these small businesses living only with a few months of cash flow, it can be devastating when something as significant as the COVID-19 hits. So, how can these businesses survive the times coming ahead? While there are no set rules, here are a few tips that can help you plan your finances better and step into the coming year stronger.
Create a Three-Month Financial Plan
Every small business has some key expenses, like employee salaries, office rent, raw materials, utility bills etc. Further expenses range from industry to industry. It’s prudent to evaluate your expenses completely, what are the immediate and important ones, and which ones can be deferred. Gain control of the miscellaneous expenses and plan a way to contain them. Spend only on practical necessities that will help your business grow in the longer run. Also, look at your personal finances, and speak to people you can lean on for advice to have a realistic discussion on how to control your personal spending for the next three months. Try and cut down unnecessary and non-immediate expenses.
Assess Cash Flow
Cash flow is the backbone of any organisation, particularly in times as these. Discuss your financial matters with CA and arrive at decisions related to investments on infrastructure, team hiring, fund flow, receivables, and liabilities. Invest in technology and business management software that can help you give a complete picture of your finances and projections in the future. There are several simple and easy to use business management software that help provide a complete detail of company’s financial health, which can assist you in better financial planning.
Establish an Emergency Fund
The pandemic has outlined several areas to be considered which were largely neglected. One such spot is establishing an emergency fund. Ensure your financial tools enable you to keep track of finances at each stage, thereby helping you easily establish an emergency fund when a crisis as this arises. COVID-19 might have built a situation of uncertainty, but things have started to look optimistic again.
Smart and rational financial decisions and focus on what is really important for your business will help any business overcome the challenges and bounce back stronger for a brighter future. Remember, the only way to survive this is to Address, Adapt and Amend.